A DIFC family office can coordinate a family’s administration, reporting and governance. It serves a different purpose from a company or foundation that owns assets. Start by deciding who should control the assets, which decisions need coordination and which responsibilities can remain with existing advisers. Then assess whether a full office is justified. Eligibility, financial-services permissions and tax treatment depend on the proposed arrangement. (DIFC Family Arrangements Regulations; UAE Corporate Tax Law)
For licence requirements and the available service, see our DIFC family office setup guide. This article focuses on the ownership and governance decisions that should come first.
Table of Contents
Decide which problem the office must solve
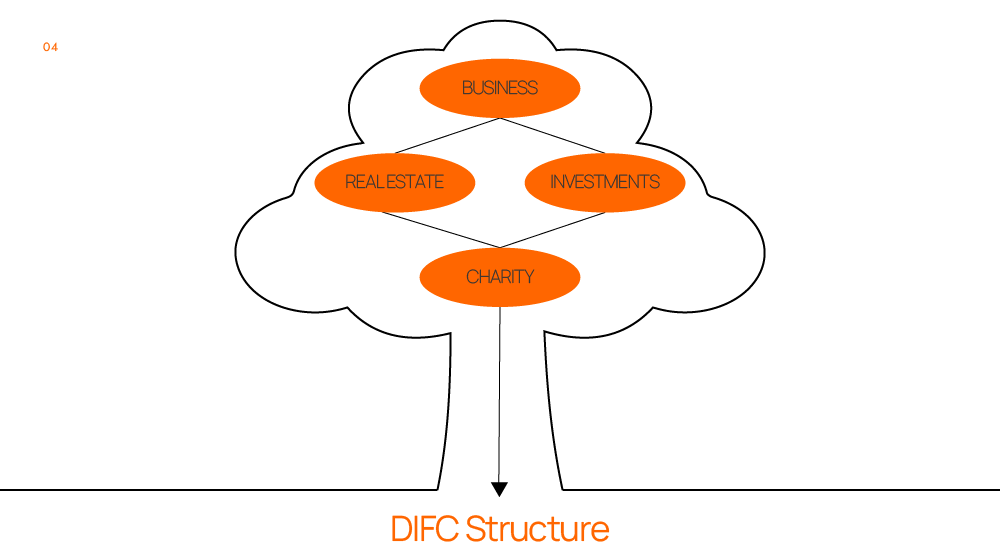
Start with a family asset and responsibility map. Record operating businesses, investment portfolios and property interests. Identify the people who control each asset and the advisers who administer it.
The family may need consolidated reporting, a succession process or a clearer separation between personal and business spending. Another family may need investment oversight across several managers. These needs produce different staffing, systems and entity choices.
Avoid adding a full office where a smaller governance or administration arrangement meets the need. Obtain an operating budget alongside the incorporation proposal.
Separate the office from the asset-owning entities
A family office does not need to own every asset or receive every investment payment. Keep contracts and bank accounts consistent with the entity that actually owns the asset or provides the service.
Review a UAE holding-company structure as a separate ownership decision.
Confirm the family-office route and eligibility
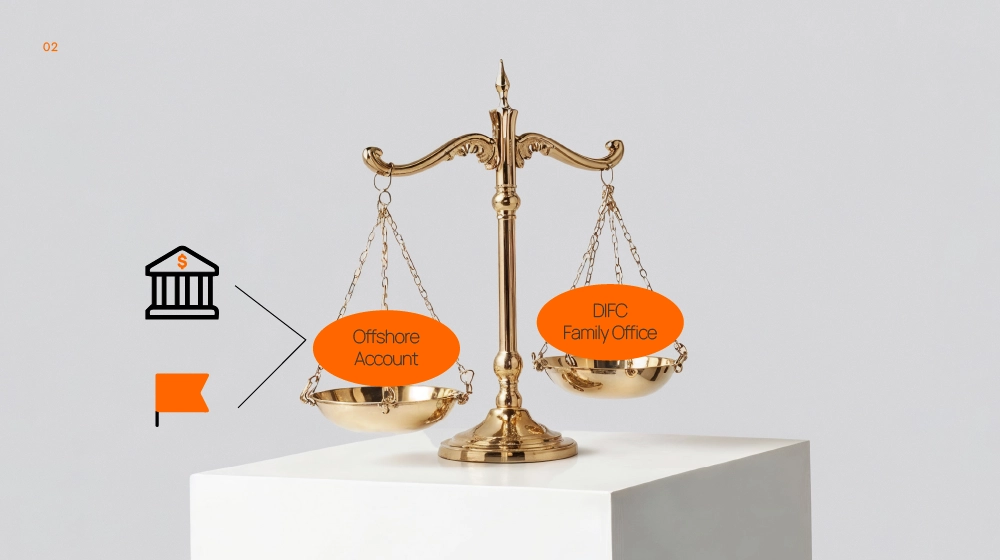
DIFC introduced its Family Arrangements Regulations in 2023. Use the current regulations and registration requirements for the proposed route. Do not assume that every family arrangement qualifies for the same licence. (DIFC Family Arrangements Regulations)
The Family Arrangements Regulations define a USD 50 million aggregate net-asset requirement for the family, measured at fair market value or, where that cannot be established, book value. This is a family eligibility test, rather than a requirement to deposit USD 50 million as the office’s share capital. Check the current Registrar application requirements alongside that test. (DIFC Family Arrangements Regulations)
A family that does not qualify for a particular office route may still have other structuring options. Assess each option’s own eligibility and permitted purpose before presenting it as an alternative.
Check the financial-services boundary
The regulations distinguish services for one family from approved arrangements for more than one family. Regulation 4.3.2 requires Registrar approval for a multi-family arrangement and DFSA authorisation where Restricted Services are provided to more than one family by way of business. Assess the actual clients and activities before offering a service. (DIFC Family Arrangements Regulations)
Do not describe all family offices as unregulated. Confirm the proposed clients, activities and any relevant exemption with the appropriate advisers and authority. A commercial registration does not settle a DFSA authorisation question.
The same discipline applies when an office expands its services. Review a new service before the office accepts an unrelated client or changes how it handles investments.
Write the governance before moving assets
Agree who can appoint the office’s directors and approve its budget. Set investment limits, distribution authority and rules for conflicts of interest. Define which decisions require family approval and which the office can make under delegated authority.
Plan for incapacity, death and the next generation joining the ownership structure. A foundation, trust or family charter does not remove the need to check each asset’s governing rules and foreign-country consequences.
Do not promise anonymity or absolute asset protection. Banks and authorities can require ownership and control information. Existing claims, guarantees and transfer rules also need review.
Assess tax across the structure
Classify the income of each entity separately. Dividends, investment gains, service fees, interest and property income do not share one automatic treatment. Confirm whether any exemption or Qualifying Free Zone Person (QFZP) treatment applies. (UAE Corporate Tax Law; Corporate Tax Law, exemptions; Qualifying Income Decision; Qualifying Activities Decision)
The family members’ countries of residence can tax their interests, distributions or benefits. A UAE vehicle does not settle foreign tax, succession or reporting obligations. Coordinate the UAE plan with advisers in the countries involved before transferring assets.
Prepare for operation after incorporation
Use separate approvals for incorporation, banking and asset transfers. Do not treat one acceptance as approval for the others.
Questions families ask
Does every family office need a foundation?
No single arrangement fits every family. Select an ownership structure after reviewing control, succession and the assets involved.
Is a DIFC family office tax-free?
No blanket exemption follows from the name or licence. Assess each entity, income stream and owner’s position. (UAE Corporate Tax Law)
Can the office serve several families?
Confirm the route and financial-services permissions before offering that service. A permission to serve one family does not establish permission to serve unrelated clients. (DFSA authorisation guidance; DIFC Family Arrangements Regulations)
Discuss your family governance needs
Bring the asset map and the decisions the family wants to coordinate. Discuss your family structure with GCG.
For help with the implementation, see our DIFC family office setup service.
Sources: DFSA authorisation guidance; DIFC Family Arrangements Regulations; UAE Corporate Tax Law; Corporate Tax Law, exemptions; Qualifying Income Decision; Qualifying Activities Decision