

JAFZA offers company-formation routes without a general requirement for a UAE national shareholder. The relevant licence still needs to cover the activity, and the company must meet JAFZA’s application and premises requirements. Confirm the legal form and intended operations before applying. Foreign ownership does not create unrestricted trading rights outside the free zone or automatic tax relief. (JAFZA formation options; Dubai Resolution 11 of 2025; UAE Corporate Tax Law)
Table of Contents
Match the licence to the operation
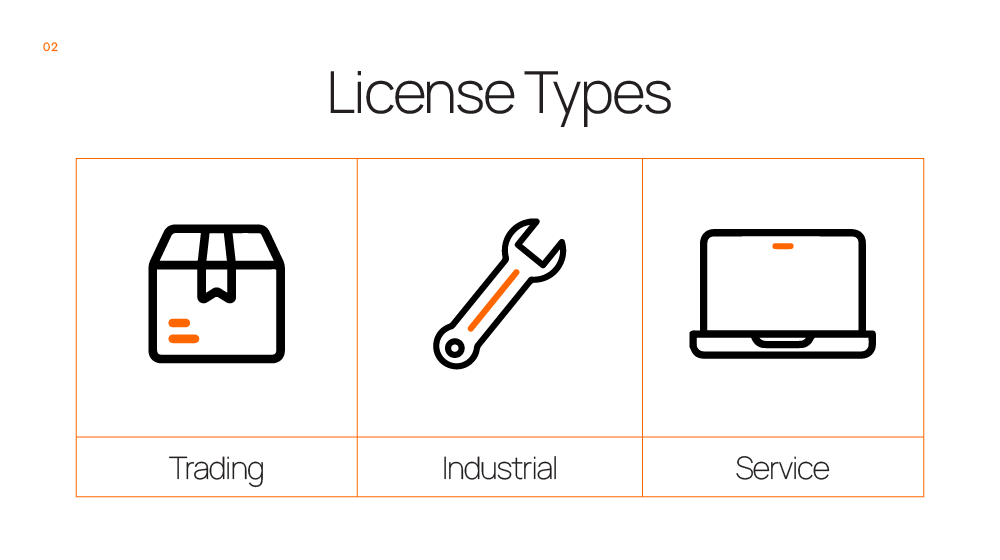
List the goods or services, customer markets and premises the company needs. A specific trading activity, general trading and an industrial operation can involve different permissions. Ask JAFZA to confirm the precise licence and activity combination.
A company importing and storing goods needs to plan customs and warehousing alongside incorporation. A service company should confirm that its proposed work fits the activity and premises offered. Avoid treating every JAFZA formation as the same trade licence. (JAFZA formation options; JAFZA licence categories)
Choose the legal form
JAFZA describes these as distinct formation options. An offshore registration is not interchangeable with a licensed operating company using offices, staff or a warehouse. (JAFZA formation options; JAFZA licence categories)
For an ownership rather than trading objective, use the holding-company setup guide.
Confirm what the ownership position does and does not mean
JAFZA’s company-formation guidance states that it has no foreign ownership restrictions. That addresses company ownership. It does not remove sector permissions or the need to meet banking, customs and immigration requirements. (JAFZA formation options; JAFZA licence categories)
Keep the word sponsor precise. A shareholder’s ownership role differs from the entity that supports an immigration application. The absence of a local shareholder does not mean the company or its staff can omit establishment and residence procedures.
Compare JAFZA with a mainland route by the actual activities, operating permissions and governance. Local shareholder requirements depend on the relevant activity and legal form.
Prepare the documents for the chosen route
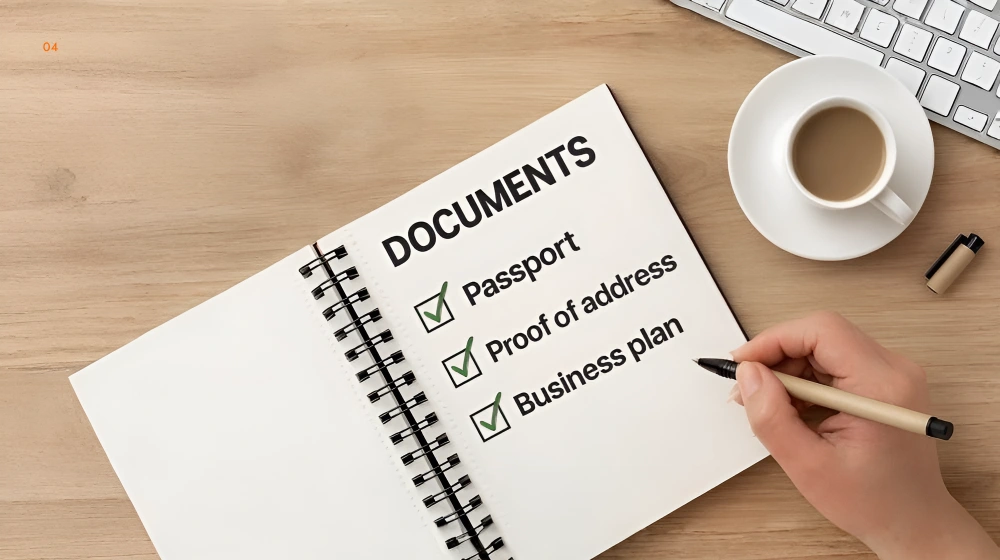
Confirm the current checklist with JAFZA. Prepare identity evidence for owners and managers, the proposed activity and a clear ownership chart. A corporate shareholder or branch can require parent-company records, resolutions and authorised-signatory evidence.
Ask which foreign documents need certification, legalisation or translation. Confirm the requirements before ordering those services. The registry and bank can request different evidence.
For premises, confirm the permitted use and any technical conditions before signing a lease. Warehouse size, industrial work and office requirements follow the actual activity rather than a generic package label. (JAFZA formation options; JAFZA licence categories)
Follow the setup and operating sequence
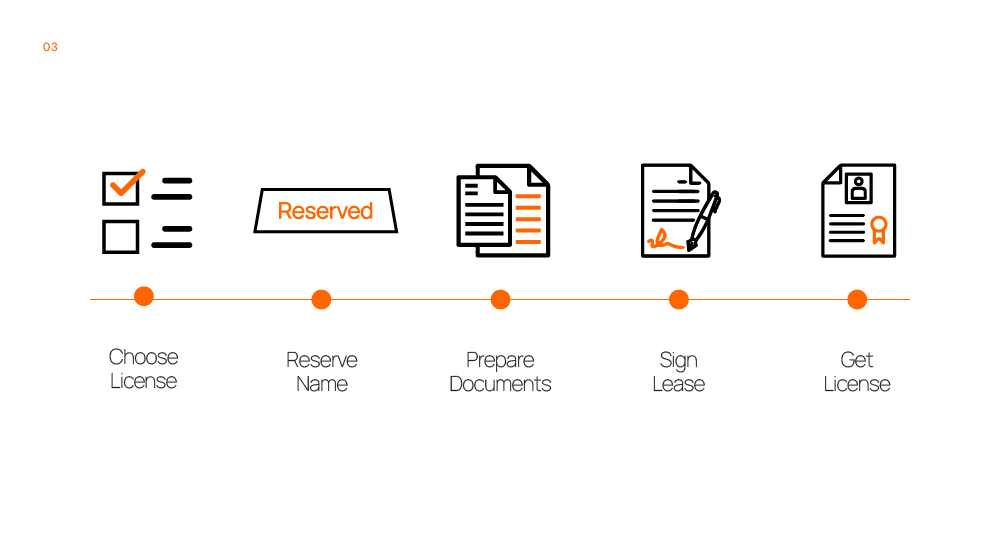
Confirm which steps depend on earlier approvals. A bank account and a residence application require separate decisions; the company licence does not guarantee them.
Plan goods movements and mainland activity
Identify who imports the goods, who owns the stock and how it reaches the customer. Confirm customs documentation and any product approvals. Do not assume free-zone registration makes every delivery duty-free.
Dubai’s outside-zone operating framework provides specified routes for eligible establishments. Confirm the relevant activity, zone approval and DET permission before planning operations outside JAFZA. (Dubai Resolution 11 of 2025)
Review corporate tax and annual administration
A JAFZA company does not receive automatic zero-tax treatment. Test the revenue and activities under the current corporate-tax rules. Distribution, logistics and other qualifying-activity categories have conditions. (UAE Corporate Tax Law; Qualifying Income Decision; Qualifying Activities Decision)
Distinguish corporate-tax Free Zone status from VAT Designated Zone treatment. Apply each regime to the actual transaction. (FTA zone-classification clarification)
Include licence and premises renewals, accounts, tax filings and any required audit in the operating budget. Track ownership and management changes with the relevant authorities and bank.
Questions applicants ask
Do I need a local Emirati shareholder?
JAFZA’s formation guidance states that there are no foreign ownership restrictions. Confirm the specific formation and regulated activity requirements. (JAFZA formation options; JAFZA licence categories)
Can I use an offshore company to run the same operation?
Do not assume the routes are interchangeable. Confirm the offshore entity’s permitted purpose and operating limits. (JAFZA formation options; JAFZA licence categories)
Is banking included in the licence approval?
No. The bank assesses the account application separately. (CBUAE due-diligence guidance)
Discuss your JAFZA structure
Bring the product list, ownership chart and premises plan. Discuss your UAE company structure with GCG.
For help with the implementation, see our UAE company formation service.
Sources: CBUAE due-diligence guidance; JAFZA formation options; JAFZA licence categories; Dubai Resolution 11 of 2025; UAE Corporate Tax Law; FTA zone-classification clarification; Qualifying Income Decision; Qualifying Activities Decision